The pipelines that bypass the Strait of Hormuz
Two matter, and they are not equivalent. One ends outside every chokepoint. The other ends inside the Red Sea, which has a chokepoint of its own.
Reviewed 9 November 2026
| Measure | Figure |
|---|---|
| Petroline design capacity | 5 million barrels a dayAramco reported 7 million in March 2025; sustained flows at that level untested. |
| Petroline in use, early 2026 | About 2 million barrels a day |
| Petroline spare | 3–5 million barrels a day |
| Petroline delivers to | Red Sea terminals, principally YanbuExit requires Bab el-Mandeb or the Suez Canal. |
| ADCOP nameplate | 1.5 million barrels a dayAbout 1.8 million reported current capacity. |
| ADCOP in use | About 1.1 million barrels a day |
| ADCOP spare | Up to 700,000 barrels a day |
| ADCOP delivers to | Fujairah, Gulf of OmanOutside the strait and outside the Red Sea. |
| Saudi NGL pipeline | 300,000 b/d, fully utilised |
| Dolphin gas pipeline | 20.5 bcm in 2025, limited spare |
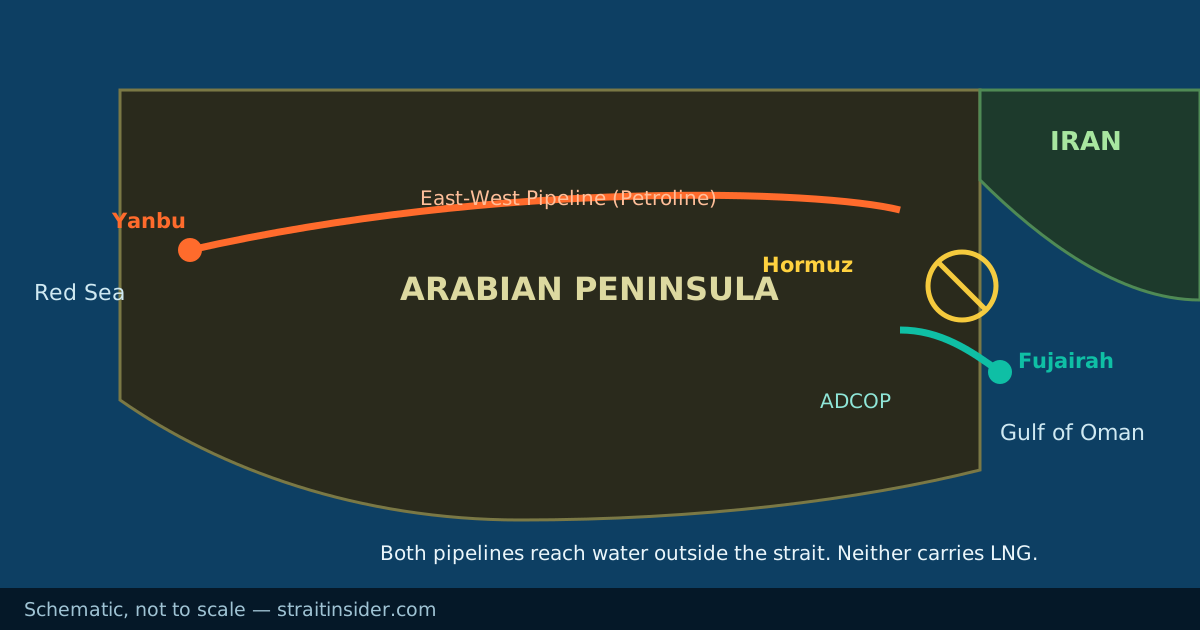
Petroline: large, under-used, and pointed at the wrong sea
The East-West Pipeline runs from Saudi Arabia’s Eastern Province oil fields across the kingdom to the Red Sea coast, principally to Yanbu. It is the single largest piece of bypass infrastructure in the region: 5 million barrels a day of design capacity, with Aramco having reported 7 million in March 2025, although the IEA notes that sustained flows at that level have not been tested.
In early 2026 it was carrying about 2 million barrels a day, leaving 3 to 5 million of headroom — by far the largest single block of spare bypass capacity available.
And it ends on the Red Sea. A cargo loading at Yanbu for Asia has to go south through Bab el-Mandeb; one bound for Europe can go north through Suez, which is itself subject to the same regional security calculation. Since Houthi forces took Yemen’s Red Sea coast in September 2026, the southern exit has been well below normal throughput. The pipeline moves oil out of the Persian Gulf; it does not move it out of the problem.
The EIA data shows this happening in practice: Bab el-Mandeb oil flow rose from 5.4 million barrels a day in the fourth quarter of 2025 to 8.1 million in the second quarter of 2026, which is Saudi rerouting arriving as extra load on a constrained waterway.
ADCOP: smaller, and the only clean escape
The Abu Dhabi Crude Oil Pipeline runs from Habshan in the UAE to Fujairah, on the eastern side of the Musandam Peninsula. That single geographic fact is what makes it different: Fujairah faces the Gulf of Oman, so a tanker loading there is already past the strait and has open ocean ahead of it with no further chokepoint.
It is the smaller of the two. Nameplate capacity is 1.5 million barrels a day, with about 1.8 million reported currently, and it carries roughly 1.1 million, leaving up to 700,000 barrels a day spare.
Fujairah’s importance in any Hormuz discussion is out of all proportion to its size, and this is why. It is the only substantial loading point in the region that is not behind a chokepoint.
What the others contribute
Saudi Arabia’s NGL pipeline carries 300,000 barrels a day and is fully utilised, so it offers nothing in a crisis.
Iran’s Jask terminal on the Gulf of Oman was built for exactly this purpose and has a nominal million barrels a day of capacity. It is effectively non-operational — its only test load was in late 2024 — which means Iran has no working bypass of its own.
For gas there is very little. The Dolphin pipeline carried almost 20.5 billion cubic metres in 2025 with limited spare capacity, and Oman’s LNG terminals, which sit outside the strait, run near full utilisation. Qatar’s position is the one to understand.
Reading nameplate capacity honestly
Pipeline capacity is quoted three ways and the differences are large. Design capacity is what the system was built for. Current or reported capacity reflects pumping and debottlenecking since. Available capacity is design or current minus what is already flowing, which is the only figure that means anything in a disruption.
For Petroline those are 5, up to 7, and 3 to 5 million barrels a day respectively. Quote the first and you overstate the relief; quote the second and you overstate it considerably, since sustained operation at 7 million is untested.
The IEA’s total of 3.5 to 5.5 million barrels a day of available bypass capacity across Saudi Arabia and the UAE is the figure to use, and it should be read with the Red Sea caveat attached to most of it. The wider picture is here.
Common questions
- How much oil can the East-West pipeline carry?
- 5 million barrels a day by design, with Aramco reporting 7 million in March 2025 though sustained flows at that level are untested. About 2 million b/d was in use in early 2026.
- Does the East-West pipeline fully bypass the Strait of Hormuz?
- It bypasses the strait but delivers to Red Sea terminals, so cargoes must then exit through Bab el-Mandeb or the Suez Canal. With Bab el-Mandeb disrupted since 2026, that is a meaningful qualification rather than a technicality.
- Why is Fujairah important?
- Because it sits on the Gulf of Oman, outside the strait and outside the Red Sea. It is the only substantial loading point in the region with open ocean ahead of it, which is why the UAE pipeline to Fujairah is the cleanest bypass available.
- Can pipelines replace the Strait of Hormuz?
- No. Available capacity covers roughly a quarter of normal transit, part of it into a constrained waterway, and there is almost no bypass capacity for LNG at all.